Business Loans Australia Business Loan Repayment Calculator
Explore potential business finance scenarios with our Business Loan Calculator. Test different borrowing amounts, interest rate assumptions and loan structures to see how various scenarios may influence your estimated repayments and overall finance costs.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide finance. Actual costs and repayments may differ.
Business Loan Details:
Important!
Business Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Business Loan Amortisation Calculator
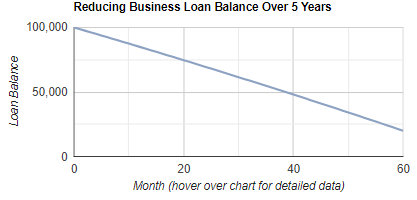
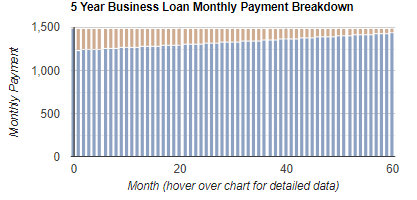
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Business Loan Repayment Calculator
Our Business Loan Repayment Calculator helps you estimate business loan repayments, compare finance options and understand the true cost of borrowing before you commit. It is important because small changes to your loan amount, interest rate, term or balloon payment can materially change cash flow, total interest and end-of-term obligations. This calculator provides an indicative estimate only and is designed to support planning and budgeting for business growth.
How to complete each section for the best result:
1. Loan Amount
Enter the amount you expect to borrow as a whole number (no dots or commas). Include any costs you plan to capitalise into the loan, such as stamp duty, registration, insurance or other applicable fees, so the estimate reflects your real financed amount.
2. Balloon or Residual Payment (optional)
Select a residual as a percentage of the purchase price. A higher residual usually reduces ongoing repayments, but increases the amount due at the end and can increase total interest over the term. Choose a residual only if you have a realistic plan to refinance, pay it out, or sell an asset to meet the final amount.
3. Term of Loan
Select the number of years you want to repay the loan. A longer term generally lowers periodic repayments but increases total interest paid. A shorter term can reduce total cost but may place pressure on cash flow.
4. Interest Rate
Select an indicative annual interest rate to run a scenario. Your actual rate depends on lender assessment and your business circumstances, so consider testing multiple rates to stress-test affordability.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a budgeting guide for regular cash flow planning. If you selected a residual, remember the final payout is additional to the periodic repayments.
2. Amortisation charts
Review the reducing loan balance over time and the split between interest and principal. Early repayments typically include a higher interest component, with principal reduction accelerating later.
General information only, not personal financial advice. It does not consider your objectives, financial situation or needs. Consider the loan contract, fees, repayment frequency, and whether the repayments remain affordable under higher rates or lower revenue, and seek professional advice if required.
Personal guarantees, collateral and security interests can affect both a business and the people behind it. This guide explains key risk concepts Australian SME owners, sole traders and company directors should understand before signing a business loan agreement. - read more
Falling behind on a business loan can lead to arrears, fees, default action, enforcement against secured assets and potential claims under personal guarantees. This guide explains the main risks Australian business owners should understand and the practical steps to consider early. - read more
In the dynamic world of business, navigating credit challenges is a reality for many Australian business owners. These challenges can stem from various sources, including unpaid customer invoices, unexpected expenses, or the complexities of managing cash flow. Such hurdles often come at inopportune moments, leading to recurring stress for entrepreneurs trying to maintain a stable financial standing. - read more
A business loan can support cash flow, equipment purchases, expansion, marketing or other planned investment. For Australian business owners, the process works best when borrowing needs, documentation, lender requirements and repayment capacity are considered before an application is submitted. - read more
Starting or growing a business often requires capital for equipment, stock, staffing, premises or day-to-day cash flow. Business loans can help fund those needs, but the details in the loan agreement determine how the finance works, what it may cost and what obligations the borrower accepts. - read more
When comparing business loans, it's important to look beyond the interest rate and understand the range of fees and charges that may apply. Business loan costs can include establishment fees, ongoing account fees, early repayment fees and other charges that contribute to the total cost of borrowing. - read more
Your credit score is a crucial factor that lenders examine when you apply for a loan. It acts as a numerical representation of your creditworthiness, helping lenders to determine the risk involved in offering you a loan. Essentially, it helps them predict your ability to repay the loan based on your past financial behaviour. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent has sharpened the planning task for Australian businesses already balancing higher input costs, cautious customers and tighter margins. For SMEs with variable-rate debt, overdrafts, asset finance or upcoming refinancing decisions, the latest move is less a single shock than another reason to revisit repayment assumptions before small pressures become larger cash flow problems. - read more
Australian SME borrowing activity appears to have regained momentum, with newly reported Banjo Loans Barometer data for the quarter to 30 September 2026 pointing to stronger loan applications, more loans drawn and a continued focus on cash buffers. The result is notable because it follows months of more cautious borrowing signals from parts of the small business market, and suggests many firms are not simply waiting for conditions to improve before reviewing their funding position. - read more
Australian SMEs planning their next round of investment are increasingly looking beyond traditional bank funding, with new ScotPac SME Growth Index findings reported by Inside Small Business on 22 October 2026 showing non-bank finance has reached a record share of intended funding use. The result is a notable signal for business owners and finance managers: the question is no longer simply whether credit is available, but which structure best matches the timing, risk and cash flow profile of the business. - read more
Latest Australian business survey reporting is sending a practical message to owners and finance managers: trading conditions may be holding up in parts of the economy, but confidence remains fragile. For SMEs, that mix matters. When revenue is uneven, input costs are sticky and customers are cautious, the timing and structure of new borrowing can become just as important as the headline interest rate. - read more
A tax change now working through Australian business finances deserves close attention from owners, directors and finance managers. Since 1 July 2025, the ATO’s general interest charge and shortfall interest charge have no longer been tax-deductible. For businesses carrying overdue tax or correcting underpaid obligations, that can lift the effective after-tax cost of falling behind. - read more
Australia’s move towards Payday Super is more than a compliance update for employers. For many small and medium-sized businesses, it changes the rhythm of payroll-related cash outflows and places a sharper focus on whether day-to-day liquidity is strong enough to meet obligations as they fall due. - read more
Latest market reporting around specialist SME lender Judo Bank points to a business credit market that is not shutting down, but is becoming more deliberate. The lender’s continued focus on relationship-led lending, deposits and small to medium-sized business borrowers suggests demand for finance remains present among firms with clear plans and serviceable cash flow. - read more