Business Loans Australia Truck Loan Repayment Calculator
Use our Truck Loan Calculator to estimate repayments, compare finance options, and plan your purchase with ease. Fast, simple, and tailored for Australian businesses and drivers.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide finance. Actual costs and repayments may differ.
Truck Loan Details:
Important!
Truck Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Truck Loan Amortisation Calculator
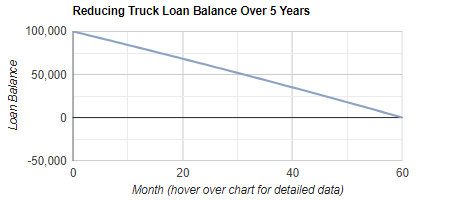
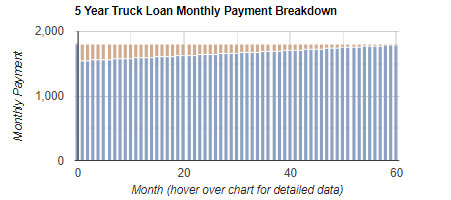
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Truck Loan Repayment Calculator
Our Truck Loan Repayment Calculator helps Australian drivers and businesses estimate loan repayments before you commit. It is designed to support budgeting, cash flow planning, and comparing truck finance scenarios by showing how changes to price, deposit, term, and interest rate can affect your repayments and total interest cost.
How to complete the calculator for the most accurate estimate
1. Purchase Price
Enter the total purchase price of the truck you plan to finance. Consider including eligible on-road and purchase-related costs that may be financed (for example registration, insurance, or other costs where applicable). Use whole numbers only, without commas or decimals.
2. Deposit or Trade-in Value
If you are paying an upfront deposit or using a trade-in, enter that amount here. This reduces the amount you need to borrow and can lower repayments and total interest. Use whole numbers only.
3. Term of Loan (Years)
Select the loan term in years. In general, a longer term can reduce the periodic repayment but may increase the total interest paid over the life of the loan. Choose a term that suits your expected truck usage and business cash flow.
4. Interest Rate (Percent per annum)
Select an interest rate to model your scenario. Rates vary by lender and borrower circumstances, so it can be helpful to test a conservative rate as well as an optimistic one.
5. Calculate
Select calculate to generate your repayment estimate and repayment breakdown visuals.
How to interpret your results
1. Repayment estimate
Use this as a guide to affordability and budgeting. If the repayment is tight, test a higher deposit, shorter term, or different interest rate.
2. Amortisation and graphs
Review how the loan balance reduces over time, and how each repayment typically shifts from mostly interest early on to more principal later. This can help with planning for refinancing, early payout, or upgrade timing.
ASIC compliance note: This calculator provides information only and is not financial or credit advice. Results are estimates and may not include all fees, charges, taxes, residuals or balloon payments. Consider your objectives and financial situation, and seek independent advice or a lender quote before proceeding.
When it comes to applying for a loan, having the right documents is crucial. Whether you're looking to buy a home, start a new business, or refinance an existing loan, documentation can make or break your application. It serves as evidence of your financial health, providing lenders with a clear picture of your ability to repay the loan. - read more
Mezzanine finance is a hybrid form of business funding that sits between senior debt and equity. For Australian businesses considering acquisitions, it can help bridge a funding gap when conventional lending is not enough and owners want to limit immediate equity dilution. - read more
Business loan interest rates in Australia vary because lenders price each loan according to the product, market conditions, business risk, security, loan term and the applicant's financial position. Understanding these factors can help SMEs compare loan offers more confidently. - read more
Your credit score is a crucial factor that lenders examine when you apply for a loan. It acts as a numerical representation of your creditworthiness, helping lenders to determine the risk involved in offering you a loan. Essentially, it helps them predict your ability to repay the loan based on your past financial behaviour. - read more
Embarking on a business endeavor often requires substantial financial support, and securing a business loan can be a crucial step towards progress and expansion. A well-prepared loan application not only showcases your business in its best light but also significantly enhances the prospects of obtaining the needed funds. Attention to detail and a thorough understanding of the lending process can streamline your journey to approval. - read more
Comparing business loan features is an important part of understanding the different finance options available to your business. Loan products vary between lenders, with differences in interest rates, fees, repayment terms, borrowing limits and eligibility criteria. - read more
Business loan repayments are shaped by the amount borrowed, interest rate, loan term, repayment frequency, fees and repayment structure. Understanding how these factors interact can help Australian business owners estimate affordability and compare loan options more confidently. - read more
Latest Australian business survey reporting is sending a practical message to owners and finance managers: trading conditions may be holding up in parts of the economy, but confidence remains fragile. For SMEs, that mix matters. When revenue is uneven, input costs are sticky and customers are cautious, the timing and structure of new borrowing can become just as important as the headline interest rate. - read more
A tax change now working through Australian business finances deserves close attention from owners, directors and finance managers. Since 1 July 2025, the ATO’s general interest charge and shortfall interest charge have no longer been tax-deductible. For businesses carrying overdue tax or correcting underpaid obligations, that can lift the effective after-tax cost of falling behind. - read more
Australia’s move towards Payday Super is more than a compliance update for employers. For many small and medium-sized businesses, it changes the rhythm of payroll-related cash outflows and places a sharper focus on whether day-to-day liquidity is strong enough to meet obligations as they fall due. - read more
Latest market reporting around specialist SME lender Judo Bank points to a business credit market that is not shutting down, but is becoming more deliberate. The lender’s continued focus on relationship-led lending, deposits and small to medium-sized business borrowers suggests demand for finance remains present among firms with clear plans and serviceable cash flow. - read more
Fresh small business indicators are again pointing to a familiar challenge for Australian SMEs: trading activity may continue, but the timing of cash receipts is still creating pressure. Recent industry commentary has highlighted uneven payment behaviour, cautious customer spending and a more deliberate approach to investment among smaller firms. For owners and finance managers, that combination can make working capital planning just as important as sales growth. - read more
Late invoice payments are again emerging as a practical funding issue for Australian small and medium-sized businesses, with fresh industry commentary pointing to continued pressure across trade payments, cash reserves and day-to-day operating liquidity. For business owners, the message is clear: revenue on paper is not the same as cash in the bank. - read more
Fresh business risk signals are reinforcing a clear message for Australian SMEs: access to credit is still available, but lenders are likely to keep asking harder questions about cash flow, repayment capacity and the resilience of each borrower’s operating model. The latest commentary around business failures, trade payment pressure and sector-specific insolvency risk points to a market where credit decisions are becoming increasingly evidence-led. - read more
All finance quotes are provided free (via our secure server) and without
obligation. We respect your
privacy.
Knowledgebase
Bridging Finance: A short-term loan that covers a financial shortfall during time between the purchase of a new property and the sale of an old property.