Business Loans Australia :: News
SHARE

Share this news item!

Small Firms Tap the Brakes on Borrowing in June

Why cautious credit demand could reshape working capital decisions

Small Firms Tap the Brakes on Borrowing in June?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

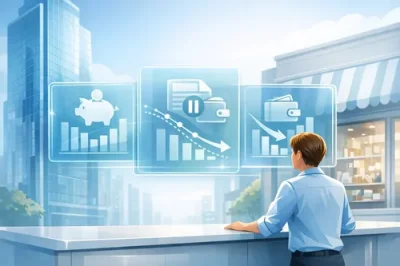
Australian small businesses appear to be moving into a more defensive phase, with new Equifax data for June 2026 pointing to a sharp divide between larger companies still borrowing for expansion and SMEs conserving cash.
The latest Business Market Pulse suggests overall business loan demand is still growing, but at a slower pace than the stronger credit activity recorded late last year.

The headline number shows national business loan demand up 3.8 per cent year-on-year, but the more important detail for SME owners is beneath the surface. Large enterprises recorded loan demand growth of 7.8 per cent, while SME loan demand was almost flat at just 0.5 per cent. Asset finance applications from SMEs also fell 5.6 per cent, signalling that many smaller operators may be delaying equipment upgrades, vehicle purchases and other productivity investments.

That caution is understandable. Many SMEs are still absorbing higher wages, rent, energy, insurance, fuel and compliance costs, while customers in some sectors are taking longer to spend or pay. In that environment, borrowing is less likely to be about aggressive expansion and more likely to be about maintaining liquidity, paying suppliers on time and protecting day-to-day operations.

For business owners, the risk is that delaying finance decisions can narrow the available choices later. A business that waits until cash flow is already stretched may face tighter lender scrutiny, fewer product options or less room to negotiate. By contrast, reviewing forecasts early can help owners compare business financing options while accounts are still orderly and repayment capacity is easier to demonstrate.

The fall in SME asset finance applications also deserves attention. Pausing investment may preserve cash in the short term, but it can also affect efficiency, delivery times and competitiveness if ageing equipment becomes a drag. Before cancelling or postponing a planned purchase, owners should model repayment capacity against conservative revenue assumptions, realistic supplier terms and seasonal cash flow movements.

This is not a signal that every SME should borrow. It is a reminder that finance strategy should be active, not reactive. The strongest position is knowing how much working capital is needed, what security is available, which loan structures suit the business, and whether secured or unsecured funding would provide the right balance of cost, speed and flexibility. In a two-speed credit market, preparedness may be the difference between choosing finance on your terms and seeking it under pressure.

Published:Tuesday, 21st Jul 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

Business Confidence Signals Put Loan Readiness Back in Focus
16 Sep 2026: Paige Estritori
Latest Australian business survey reporting is sending a practical message to owners and finance managers: trading conditions may be holding up in parts of the economy, but confidence remains fragile. For SMEs, that mix matters. When revenue is uneven, input costs are sticky and customers are cautious, the timing and structure of new borrowing can become just as important as the headline interest rate. - read more
Why ATO Interest Changes Matter for Business Borrowers
09 Sep 2026: Paige Estritori
A tax change now working through Australian business finances deserves close attention from owners, directors and finance managers. Since 1 July 2025, the ATO’s general interest charge and shortfall interest charge have no longer been tax-deductible. For businesses carrying overdue tax or correcting underpaid obligations, that can lift the effective after-tax cost of falling behind. - read more
Payday Super Puts Payroll Timing Under the Finance Microscope
02 Sep 2026: Paige Estritori
Australia’s move towards Payday Super is more than a compliance update for employers. For many small and medium-sized businesses, it changes the rhythm of payroll-related cash outflows and places a sharper focus on whether day-to-day liquidity is strong enough to meet obligations as they fall due. - read more
Specialist SME Lending Remains Open, But Discipline Matters
26 Aug 2026: Paige Estritori
Latest market reporting around specialist SME lender Judo Bank points to a business credit market that is not shutting down, but is becoming more deliberate. The lender’s continued focus on relationship-led lending, deposits and small to medium-sized business borrowers suggests demand for finance remains present among firms with clear plans and serviceable cash flow. - read more
Payment Timing Keeps Pressure on SME Working Capital
19 Aug 2026: Paige Estritori
Fresh small business indicators are again pointing to a familiar challenge for Australian SMEs: trading activity may continue, but the timing of cash receipts is still creating pressure. Recent industry commentary has highlighted uneven payment behaviour, cautious customer spending and a more deliberate approach to investment among smaller firms. For owners and finance managers, that combination can make working capital planning just as important as sales growth. - read more
Payment Delays Put Working Capital Back on the SME Agenda
12 Aug 2026: Paige Estritori
Late invoice payments are again emerging as a practical funding issue for Australian small and medium-sized businesses, with fresh industry commentary pointing to continued pressure across trade payments, cash reserves and day-to-day operating liquidity. For business owners, the message is clear: revenue on paper is not the same as cash in the bank. - read more
Rising Business Failure Risk Puts Cash Flow Back in the Lending Spotlight
04 Aug 2026: Paige Estritori
Fresh business risk signals are reinforcing a clear message for Australian SMEs: access to credit is still available, but lenders are likely to keep asking harder questions about cash flow, repayment capacity and the resilience of each borrower’s operating model. The latest commentary around business failures, trade payment pressure and sector-specific insolvency risk points to a market where credit decisions are becoming increasingly evidence-led. - read more


Business Loans Articles

Flexible Business Financing in Australia: Options, Features and Application Basics
Flexible business financing can help Australian startups and small businesses match funding to cash flow, growth plans and operational needs. This guide explains common finance options, flexible loan features, lender considerations and practical steps for preparing a business loan application. - read more
Common Mistakes to Avoid During the Business Loan Application Process
Many Australian business owners find securing a business loan to be a daunting task, primarily because of the detailed documentation required and the common pitfalls that can occur at various stages of the application. - read more
Business Loan Eligibility Criteria in Australia: What Lenders Commonly Assess
Business loan eligibility in Australia depends on a lender's assessment of your business finances, credit profile, repayment capacity, loan purpose, security and supporting documents. Understanding these common criteria can help you prepare before applying. - read more
Mezzanine Finance for Business Acquisitions in Australia
Mezzanine finance is a hybrid form of business funding that sits between senior debt and equity. For Australian businesses considering acquisitions, it can help bridge a funding gap when conventional lending is not enough and owners want to limit immediate equity dilution. - read more
Breaking Down Barriers: How to Overcome Delays in Business Loan Approvals
Embarking on a business endeavor often requires substantial financial support, and securing a business loan can be a crucial step towards progress and expansion. A well-prepared loan application not only showcases your business in its best light but also significantly enhances the prospects of obtaining the needed funds. Attention to detail and a thorough understanding of the lending process can streamline your journey to approval. - read more
Start-Up Loans in Australia: How New Businesses Can Access Capital
Starting a business in Australia often requires capital before revenue is consistent. This guide explains how start-up loans and other business finance options may help new businesses fund operations, equipment, technology or growth, and what lenders commonly look for before offering finance. - read more
Understanding Business Loan Terms and Conditions: A Guide for New Business Owners
Starting or growing a business often requires capital for equipment, stock, staffing, premises or day-to-day cash flow. Business loans can help fund those needs, but the details in the loan agreement determine how the finance works, what it may cost and what obligations the borrower accepts. - read more

Need Help Finding a Loan?

Business Loan Repayment Calculator

Business Loan Repayment Calculator

Business Loans Australia Weekly News Briefing

Business Loans Australia Weekly News Briefing

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.

All finance quotes are provided free (via our secure server) and without obligation.
We respect your privacy.

Knowledgebase
Debt Consolidation:
Taking advantage of lower interest rates that may be available by the grouping of multiple loans into one, lower interest rate loan.