Business Loans Australia :: Articles

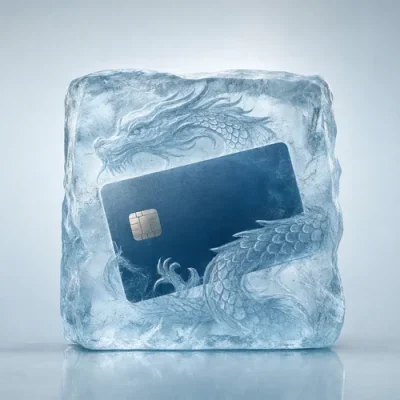
How to freeze the Plastic Debt Dragon in Your Wallet

How can I stop my credit card debt from growing and start building wealth?

How to freeze the Plastic Debt Dragon in Your Wallet

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Are you scared to open your wallet knowing there is a fire snorting dragon lurking in there? You don't need to be afraid of your credit card, you can make it your friend. Here is a plan to choke the dragon and replace it with a friendly furry critter so you can start creating wealth in your life.

Credit Card debt. Freeze the fire breathing dragon in your wallet and start living.

Are your credit cards growing and multiplying like rabbits in your wallet?  Whilst they may grow like rabbits they breathe fire and bite like a dragon.

Credit card debt growing? One card becomes two, two become three and three become four.

First you had a card with $3000 debt limit and now you have $30,000 debt limit and you are asking what happened?

Crazy thing apart from the first one which you thought you needed, I bet you never asked for another one, they were given to you!

Steps to stop this madness.

The best way to start slaying the dragon is to look at what you are spending in a day, a week and a month.

We can spend thousands a month and not see anything for it  and worst still you don't even see yourself doing it. I once asked a person why they did what they did, the response flawed me:

"I don't know I just do what I do. It's like a habit"!

What I started to realize that this was me, this caused me to look at everything and ask: am I on auto pilot  in this situation?

  •  Do I need it or do I just think I need it?
  •  Am I being lazy or is there a better option?
  •  Is this good for me?
  • Is this just advertising I am reacting to?
  • Is this just peer pressure that I am doing this?

The answers shocked me!   

I can't tell you what an impact it had on me and my lifestyle. I looked at everything differently.

Business Loans Australia Weekly News Briefing

Podcast Cover Image This week: non?bank lenders tighten as defaults rise; Commonwealth e?invoicing and 10?business?day payment terms start rolling out; more SMEs plan Black Friday and many will use credit, so plan margins and repayments; and a fresh cyber incident prompts checks on invoicing and payments. Practical steps focus on cash?flow planning, readiness for e?invoicing, careful use of credit, and basic cyber controls—plus resources at business?loans.com.au.
Stop now and quietly think why you are living the away you do?

Are credit cards helping you to live the way you want to live or are they just breathing fire onto and reinforcing a habit thats not very helpful and causing you pain?   

If you are honest to yourself you may well understand something very important about your day.

You are on auto-pilot for most of it and you automatically do things that you have stopped needing. You are only doing it because its a habit. Sit down and work out what you spend a week on this type of expenditure. It will amaze you.

Now put 75% of what your auto pilot expenditure into a wallet or purse and start paying cash for everything during the week..

And remind yourself daily:

  • When it s gone, its gone 
  • No more till next week. 

If you are not inclined to take on the dragon here is another way!

A simpler and quicker method is to consolidate your debt into a lower rate of interest loan.  Either personal loan or a mortgage.

What you are doing is taking the  dragons out of the purse and wallet and putting in a friendly little critter to replace them.The debt card. Consolidate the debt. Find a finance or mortgage broker who will help you through the process.

Published: Monday, 23rd Aug 2021
Author: 150

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Business Loans Articles

How Business Loan Interest Rates Work in Australia
Business loan interest rates in Australia vary because lenders price each loan according to the product, market conditions, business risk, security, loan term and the applicant's financial position. Understanding these factors can help SMEs compare loan offers more confidently. - read more
From Setbacks to Success: Overcoming Credit Challenges and Fueling Business Growth
In the dynamic world of business, navigating credit challenges is a reality for many Australian business owners. These challenges can stem from various sources, including unpaid customer invoices, unexpected expenses, or the complexities of managing cash flow. Such hurdles often come at inopportune moments, leading to recurring stress for entrepreneurs trying to maintain a stable financial standing. - read more
Business Loan Refinancing and Sustainable Business Growth
Business loan refinancing involves replacing existing debt with a new loan under different terms. For Australian businesses, refinancing may help improve cash flow, simplify debt management or align repayments with longer-term growth plans, but the costs and trade-offs need to be assessed carefully. - read more
Secured vs Unsecured Business Loans in Australia: Key Differences
Secured and unsecured business loans work differently, especially when it comes to collateral, interest rates, borrowing limits, documentation and repayment terms. Understanding these differences can help Australian business owners compare funding options more clearly before making an enquiry or application. - read more
How to Compare Business Loan Features Before You Apply
Comparing business loan features is an important part of understanding the different finance options available to your business. Loan products vary between lenders, with differences in interest rates, fees, repayment terms, borrowing limits and eligibility criteria. - read more
Common Mistakes to Avoid During the Business Loan Application Process
Many Australian business owners find securing a business loan to be a daunting task, primarily because of the detailed documentation required and the common pitfalls that can occur at various stages of the application. - read more
Start-Up Loans in Australia: How New Businesses Can Access Capital
Starting a business in Australia often requires capital before revenue is consistent. This guide explains how start-up loans and other business finance options may help new businesses fund operations, equipment, technology or growth, and what lenders commonly look for before offering finance. - read more

Finance News

ABS Lending Data Shows Construction Finance Rebound
18 Nov 2026: Paige Estritori
Australian business finance data is showing a sharper split between borrowers funding new construction activity and those stepping back from property purchases. The Australian Bureau of Statistics’ September quarter 2026 Lending Indicators, released on 11 November, reported seasonally adjusted new business loan commitments for construction at $17.2 billion, up 27.6 per cent over the quarter and 51.8 per cent over the year. Business loan commitments for property purchases, by contrast, fell 6.4 per cent over the quarter to $25. - read more
RBA Rate Rise Puts SME Repayment Buffers Back in View
11 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent has sharpened the planning task for Australian businesses already balancing higher input costs, cautious customers and tighter margins. For SMEs with variable-rate debt, overdrafts, asset finance or upcoming refinancing decisions, the latest move is less a single shock than another reason to revisit repayment assumptions before small pressures become larger cash flow problems. - read more
SME Borrowing Rebound Puts Planning Ahead of Panic
04 Nov 2026: Paige Estritori
Australian SME borrowing activity appears to have regained momentum, with newly reported Banjo Loans Barometer data for the quarter to 30 September 2026 pointing to stronger loan applications, more loans drawn and a continued focus on cash buffers. The result is notable because it follows months of more cautious borrowing signals from parts of the small business market, and suggests many firms are not simply waiting for conditions to improve before reviewing their funding position. - read more
SMEs Turn to Non-Bank Funding as Investment Plans Hold Up
28 Oct 2026: Paige Estritori
Australian SMEs planning their next round of investment are increasingly looking beyond traditional bank funding, with new ScotPac SME Growth Index findings reported by Inside Small Business on 22 October 2026 showing non-bank finance has reached a record share of intended funding use. The result is a notable signal for business owners and finance managers: the question is no longer simply whether credit is available, but which structure best matches the timing, risk and cash flow profile of the business. - read more
Business Confidence Signals Put Loan Readiness Back in Focus
16 Sep 2026: Paige Estritori
Latest Australian business survey reporting is sending a practical message to owners and finance managers: trading conditions may be holding up in parts of the economy, but confidence remains fragile. For SMEs, that mix matters. When revenue is uneven, input costs are sticky and customers are cautious, the timing and structure of new borrowing can become just as important as the headline interest rate. - read more
Why ATO Interest Changes Matter for Business Borrowers
09 Sep 2026: Paige Estritori
A tax change now working through Australian business finances deserves close attention from owners, directors and finance managers. Since 1 July 2025, the ATO’s general interest charge and shortfall interest charge have no longer been tax-deductible. For businesses carrying overdue tax or correcting underpaid obligations, that can lift the effective after-tax cost of falling behind. - read more
Payday Super Puts Payroll Timing Under the Finance Microscope
02 Sep 2026: Paige Estritori
Australia’s move towards Payday Super is more than a compliance update for employers. For many small and medium-sized businesses, it changes the rhythm of payroll-related cash outflows and places a sharper focus on whether day-to-day liquidity is strong enough to meet obligations as they fall due. - read more


Knowledgebase
Margin Call:
A demand by a broker that an investor deposit additional money or securities into the account to cover possible losses.