Business Loans Australia :: Articles

Five Worst Credit Card Mistakes

What are the five worst credit card mistakes to avoid?

Five Worst Credit Card Mistakes

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Credit cards can be an excellent way to manage your finances ... they can even be an investment tool. However your credit card can quickly become your enemy if not used correctly. Here are five of the worst mistakes most credit card holders make. If you can avoid these mistakes, you will benefit greatly.

Listed below are five worst mistakes most credit card holder make. If you can avoid these mistakes, you will benefit a lot.

1. Too many credit cards:

In most cases, a single credit card is sufficient to meet all the credit needs in a person's life.

More than one card leads to greater temptation resulting in inviting greater credit risk over a long run.

Multiple credit cards or credit accounts leave the lender with a question that the account holder must be spending all the money on the card.

2. Misunderstanding introductory rates:

Introductory rates on them are often low.

Many people get enticed by these rates. However, they give least attention to the rates that are levied once the introductory period is over, which can be as high as 20 percent.

3. Not reading the fine print:

This is the most common credit card mistake committed by a majority of people.

This is one strategy that companies apply to escape from legal entangles and also attract customers.

Most of the terms and conditions, including the interest rates, at the end of the introductory period are written in a fine print at the bottom or at the end of the brochure.

It is important to read these conditions in order to have a better understanding about the benefits offered by a particular card.

Business Loans Australia Weekly News Briefing

Podcast Cover Image This week: the RBA lifted the cash rate to about 4.85% on Tuesday, pushing up variable business borrowing costs. David Jones entered voluntary administration on Thursday, highlighting retail stress and supplier risk. A parliamentary inquiry is examining a proposed 30% minimum tax on discretionary trusts, with calls to grandfather firms under $10m turnover. And more SMEs plan Black Friday promotions, but many rely on credit for stock and lack margin discipline. Takeaways: refresh repayment estimates, tighten credit control, scenario‑plan trust structures, and model cash flow for sales events. Visit business‑loans.com.au for guides and calculators.

4. Making minimum payments:

This is another common mistake committed by consumers.

Credit cards should be used only during emergencies.

People should understand that credit cards offer money on credit but are not a form of income.

It is important to pay off the credit at the end of every month. With minimum payments, the trouble is going to increase further.

This is because the interest rates on the balance amount will be higher making it difficult to pay off loans for a long time.

5. Paying bills late:

When one wants to pay the credit card bill, it is better to pay that well ahead of time.

Most of the companies charge late-payment fees.

Apart from this, late payment of bills gets reflected in the credit reports, thereby making it difficult to obtain loans at better terms when one goes for any loans in the future.

Published: Tuesday, 24th Aug 2021
Author: 85

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Business Loans Articles

Cash Flow and Working Capital: Practical Strategies for Australian Business Growth
Cash flow is the movement of money into and out of a business. Working capital is the short-term funding available after current liabilities are considered. Together, they help a business meet day-to-day obligations, manage timing gaps and plan for growth opportunities. - read more
Mezzanine Finance for Business Acquisitions in Australia
Mezzanine finance is a hybrid form of business funding that sits between senior debt and equity. For Australian businesses considering acquisitions, it can help bridge a funding gap when conventional lending is not enough and owners want to limit immediate equity dilution. - read more
Business Liquidity Financing Options in Australia
Liquidity is a vital part of business financial health. It describes how readily a business can meet short-term obligations, manage cash flow and respond to changing conditions without unnecessary financial strain. - read more
Customized Leasing Solutions: Finding the Right Terms for Your Business Needs
Equipment leasing presents a strategic financial opportunity for Australian businesses seeking to maximize operational efficiency without the hefty price tag of purchasing. As many companies strive to stay competitive and agile in a bustling economic landscape, the importance of flexible asset acquisition cannot be understated. - read more
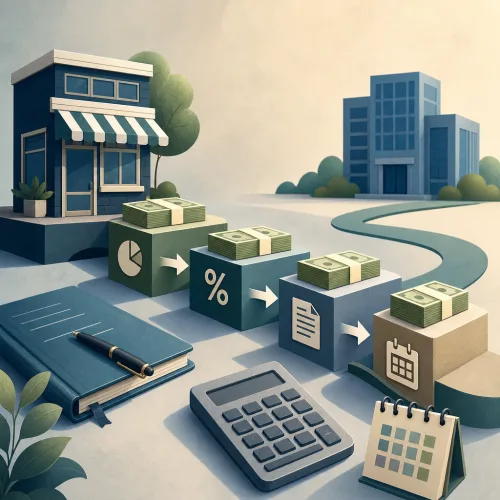
Understanding Business Loan Repayments: How Repayment Amounts Are Calculated
Business loan repayments are shaped by the amount borrowed, interest rate, loan term, repayment frequency, fees and repayment structure. Understanding how these factors interact can help Australian business owners estimate affordability and compare loan options more confidently. - read more
Planning How to Use a Business Loan in Australia
A business loan can support cash flow, investment, expansion or operational improvements, but the way the funds are planned and managed matters. This guide explains how Australian businesses can assess borrowing needs, match loan funds to clear objectives, plan repayments and monitor outcomes without taking on unnecessary financial strain. - read more
Start-Up Loans in Australia: How New Businesses Can Access Capital
Starting a business in Australia often requires capital before revenue is consistent. This guide explains how start-up loans and other business finance options may help new businesses fund operations, equipment, technology or growth, and what lenders commonly look for before offering finance. - read more

Finance News

SME Borrowing Rebound Puts Planning Ahead of Panic
04 Nov 2026: Paige Estritori
Australian SME borrowing activity appears to have regained momentum, with newly reported Banjo Loans Barometer data for the quarter to 30 September 2026 pointing to stronger loan applications, more loans drawn and a continued focus on cash buffers. The result is notable because it follows months of more cautious borrowing signals from parts of the small business market, and suggests many firms are not simply waiting for conditions to improve before reviewing their funding position. - read more
SMEs Turn to Non-Bank Funding as Investment Plans Hold Up
28 Oct 2026: Paige Estritori
Australian SMEs planning their next round of investment are increasingly looking beyond traditional bank funding, with new ScotPac SME Growth Index findings reported by Inside Small Business on 22 October 2026 showing non-bank finance has reached a record share of intended funding use. The result is a notable signal for business owners and finance managers: the question is no longer simply whether credit is available, but which structure best matches the timing, risk and cash flow profile of the business. - read more
Business Confidence Signals Put Loan Readiness Back in Focus
16 Sep 2026: Paige Estritori
Latest Australian business survey reporting is sending a practical message to owners and finance managers: trading conditions may be holding up in parts of the economy, but confidence remains fragile. For SMEs, that mix matters. When revenue is uneven, input costs are sticky and customers are cautious, the timing and structure of new borrowing can become just as important as the headline interest rate. - read more
Why ATO Interest Changes Matter for Business Borrowers
09 Sep 2026: Paige Estritori
A tax change now working through Australian business finances deserves close attention from owners, directors and finance managers. Since 1 July 2025, the ATO’s general interest charge and shortfall interest charge have no longer been tax-deductible. For businesses carrying overdue tax or correcting underpaid obligations, that can lift the effective after-tax cost of falling behind. - read more
Payday Super Puts Payroll Timing Under the Finance Microscope
02 Sep 2026: Paige Estritori
Australia’s move towards Payday Super is more than a compliance update for employers. For many small and medium-sized businesses, it changes the rhythm of payroll-related cash outflows and places a sharper focus on whether day-to-day liquidity is strong enough to meet obligations as they fall due. - read more
Specialist SME Lending Remains Open, But Discipline Matters
26 Aug 2026: Paige Estritori
Latest market reporting around specialist SME lender Judo Bank points to a business credit market that is not shutting down, but is becoming more deliberate. The lender’s continued focus on relationship-led lending, deposits and small to medium-sized business borrowers suggests demand for finance remains present among firms with clear plans and serviceable cash flow. - read more
Payment Timing Keeps Pressure on SME Working Capital
19 Aug 2026: Paige Estritori
Fresh small business indicators are again pointing to a familiar challenge for Australian SMEs: trading activity may continue, but the timing of cash receipts is still creating pressure. Recent industry commentary has highlighted uneven payment behaviour, cautious customer spending and a more deliberate approach to investment among smaller firms. For owners and finance managers, that combination can make working capital planning just as important as sales growth. - read more


Knowledgebase
Mortgage Insurance:
Insurance that protects a lender in case a borrower defaults on their mortgage.