Business Loans Australia :: Articles

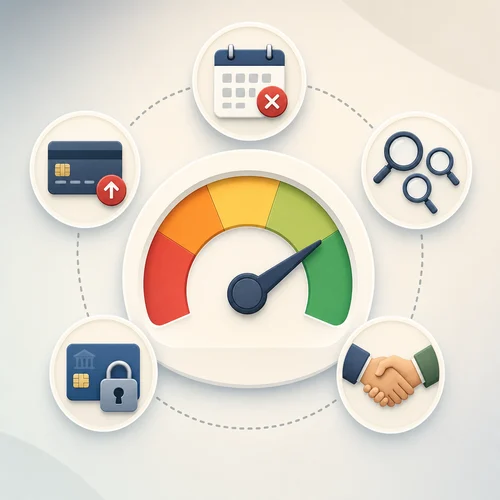
5 Credit Killers

What are the top factors that can damage your credit score?

5 Credit Killers

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

A good credit score speaks volumes about your financial habits. It's the evidence most creditors need to evaluate your credit worthiness.
Interestingly, there are some credit killers that even people maintaining good credit scores would unwittingly be a part of, which will be their undoing when applying for credit facilities in the future.
These mistakes may seem to be insignificant, but when the time comes, you may face more problems than you expect.

Avoiding Debt

Creditors need to evaluate your financial history to approve any credit facilities.
If you have no previous or existing debts, it might adversely affect your case, as creditors have no way of checking out how you'll handle the credit you get from them.

Shopping For Rates

Looking around for the best rate may actually turn out to be bad.
Too many inquiries within a short period could damage your credit score.
Usually, if you do more than 3 or 4 inquiries within a single month, you are likely to scare the lenders. For the same reasons, transferring the balances on your credit cards could be a bad idea as well.

Assuming There's a Grace Period

If you are late on a payment by even one day, you are late, period.
Never assume there's a grace period for late payments, because it only affects your credit score negatively.

Closing Old Accounts

Because your relevant transaction history also gets erased when you close your old accounts, your credit history is shortened and it may lower your credit score.
If you want to close your old accounts, close everything except the oldest account, which will leave a longer history.

Co-signing Loans

The obvious problem here is that the primary borrower's mistakes will end up on your credit report as well.

Business Loans Australia Weekly News Briefing

Podcast Cover Image This week: ASIC sues CBA over alleged overcharging of business customers; national business conditions soften with SA confidence at a multi‑year low; a major banks update shows rising arrears and higher provisions despite ongoing business‑lending growth; and a scam alert on fake Google Business Profile calls. Practical pointers: audit bank fees, stress‑test cash flow post‑RBA hike, prepare clean financials for lender reviews, and brief staff to spot scams. Visit business‑loans.com.au for guides, tools and calculators.
Published: Sunday, 1st Aug 2021
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Business Loans Articles

Personal Guarantees and Security for Business Loans in Australia
Personal guarantees, collateral and security interests can affect both a business and the people behind it. This guide explains key risk concepts Australian SME owners, sole traders and company directors should understand before signing a business loan agreement. - read more
Business Loan Fees Explained: Understanding the Total Cost of Borrowing
When comparing business loans, it's important to look beyond the interest rate and understand the range of fees and charges that may apply. Business loan costs can include establishment fees, ongoing account fees, early repayment fees and other charges that contribute to the total cost of borrowing. - read more
Common Mistakes to Avoid When Evaluating Your Refinancing Options
Refinancing can be a powerful tool for small and medium enterprises (SMEs) in Australia. It offers an opportunity to restructure debt, potentially secure better interest rates, and the possibilities of improved cash flow - all critical elements for maintaining and growing a business. Given the dynamic nature of financial markets, refinancing can provide businesses with a strategic advantage to manage their finances more effectively. - read more
Cash Flow and Working Capital: Practical Strategies for Australian Business Growth
Cash flow is the movement of money into and out of a business. Working capital is the short-term funding available after current liabilities are considered. Together, they help a business meet day-to-day obligations, manage timing gaps and plan for growth opportunities. - read more
Startup Loan vs Business Line of Credit: Which Funding Option Fits Your Business?
Starting or growing a business often requires funding for equipment, premises, stock, staff, marketing or day-to-day cash flow. Two common options are a startup loan and a business line of credit. They can both provide access to capital, but they work in different ways and suit different funding needs. - read more
Business Loan Refinancing and Sustainable Business Growth
Business loan refinancing involves replacing existing debt with a new loan under different terms. For Australian businesses, refinancing may help improve cash flow, simplify debt management or align repayments with longer-term growth plans, but the costs and trade-offs need to be assessed carefully. - read more
Business Loan Borrowing Capacity and Repayment Capacity in Australia
Business loan borrowing capacity and repayment capacity in Australia are commonly assessed through cash flow, revenue, profitability, existing debts, loan purpose, security, credit history and supporting documents. Understanding these factors can help business owners prepare before applying for finance. - read more

Finance News

SME Borrowing Rebound Puts Planning Ahead of Panic
04 Nov 2026: Paige Estritori
Australian SME borrowing activity appears to have regained momentum, with newly reported Banjo Loans Barometer data for the quarter to 30 September 2026 pointing to stronger loan applications, more loans drawn and a continued focus on cash buffers. The result is notable because it follows months of more cautious borrowing signals from parts of the small business market, and suggests many firms are not simply waiting for conditions to improve before reviewing their funding position. - read more
SMEs Turn to Non-Bank Funding as Investment Plans Hold Up
28 Oct 2026: Paige Estritori
Australian SMEs planning their next round of investment are increasingly looking beyond traditional bank funding, with new ScotPac SME Growth Index findings reported by Inside Small Business on 22 October 2026 showing non-bank finance has reached a record share of intended funding use. The result is a notable signal for business owners and finance managers: the question is no longer simply whether credit is available, but which structure best matches the timing, risk and cash flow profile of the business. - read more
Business Confidence Signals Put Loan Readiness Back in Focus
16 Sep 2026: Paige Estritori
Latest Australian business survey reporting is sending a practical message to owners and finance managers: trading conditions may be holding up in parts of the economy, but confidence remains fragile. For SMEs, that mix matters. When revenue is uneven, input costs are sticky and customers are cautious, the timing and structure of new borrowing can become just as important as the headline interest rate. - read more
Why ATO Interest Changes Matter for Business Borrowers
09 Sep 2026: Paige Estritori
A tax change now working through Australian business finances deserves close attention from owners, directors and finance managers. Since 1 July 2025, the ATO’s general interest charge and shortfall interest charge have no longer been tax-deductible. For businesses carrying overdue tax or correcting underpaid obligations, that can lift the effective after-tax cost of falling behind. - read more
Payday Super Puts Payroll Timing Under the Finance Microscope
02 Sep 2026: Paige Estritori
Australia’s move towards Payday Super is more than a compliance update for employers. For many small and medium-sized businesses, it changes the rhythm of payroll-related cash outflows and places a sharper focus on whether day-to-day liquidity is strong enough to meet obligations as they fall due. - read more
Specialist SME Lending Remains Open, But Discipline Matters
26 Aug 2026: Paige Estritori
Latest market reporting around specialist SME lender Judo Bank points to a business credit market that is not shutting down, but is becoming more deliberate. The lender’s continued focus on relationship-led lending, deposits and small to medium-sized business borrowers suggests demand for finance remains present among firms with clear plans and serviceable cash flow. - read more
Payment Timing Keeps Pressure on SME Working Capital
19 Aug 2026: Paige Estritori
Fresh small business indicators are again pointing to a familiar challenge for Australian SMEs: trading activity may continue, but the timing of cash receipts is still creating pressure. Recent industry commentary has highlighted uneven payment behaviour, cautious customer spending and a more deliberate approach to investment among smaller firms. For owners and finance managers, that combination can make working capital planning just as important as sales growth. - read more


Knowledgebase
Personal Loan:
a loan that is granted for personal use, normally unsecured and granted by a lender on the borrower's integrity and capacity to repay